
Fiscally, the tourism sector already benefited from incentive measures, in terms of IS and IR (professional income), and in terms of VAT (application of the reduced rate of 10%). But these tax advantages were limited, in terms of IS and IR (professional income), to the hotel sector and to the turnover achieved in duly repatriated currencies. These advantages, in terms of IS and IR (professional income), will be extended by the 2018 finance law (LF), to the “tourist entertainment sector”. The activities benefiting from this extension, and falling within this so-called tourist entertainment sector, will be specified by regulation.
Thus, singers, dancers and other professional artists and entertainers, organized or not in society, can rub their hands and lick their lips, hoping to appear on the list which will be established by regulation.
For new creations or new tourist entertainment establishments, the exemption in terms of IS or IR (professional income) is total, for a period of five consecutive years, starting from the financial year during which the first foreign currency transaction was carried out.
Beyond this five-year period, the reduced rate of 17.5% for corporate tax and 20% for IR (professional income) will be applied permanently.
The exemption or taxation at the reduced rate, in terms of IS and IR, is limited to the part of the taxable base corresponding to the turnover achieved in currencies duly repatriated directly or through travel agencies.
What should we mean by “tourist entertainment”? For the moment, the law and the circular note from the DGI do not contain an answer. Perhaps the regulations, intended to define the beneficiary activities, could enlighten and designate the lucky ones.
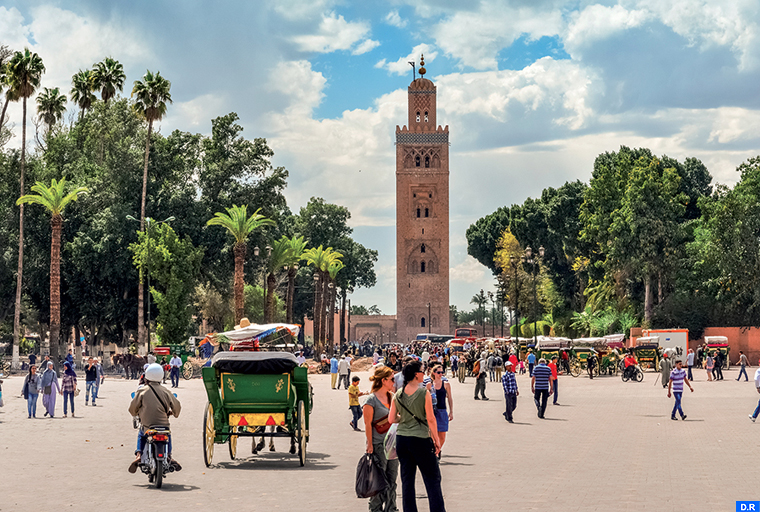
Because the term “animation” is very broad. Snake charmers, clairvoyants, musicians (…) grouped at Jamaâ El Fna, in Marrakech, are among them. This is also the case for comedians who sometimes organize large meetings. The same goes for festivals: Mawazine, in Rabat, Gnaoua, in Essaouira and others in Agadir, Asilah…
In fact, a whole niche could benefit from this extension of tax exemptions initially reserved for the hotel sector.
source: challenge.ma